News
Sign up for recent trade news that can affect your business:
If your business imports into Canada, you will need to have access to your CARM client portal. Please follow the instructions below to gain access to your account. You can find the official CBSA set up guide here.
Please have the B3 for one of your recent import transactions ready. You can find this document in the billing package you receive from Carson.
If you require assistance with any of the following steps, please contact our office and request help with CARM.
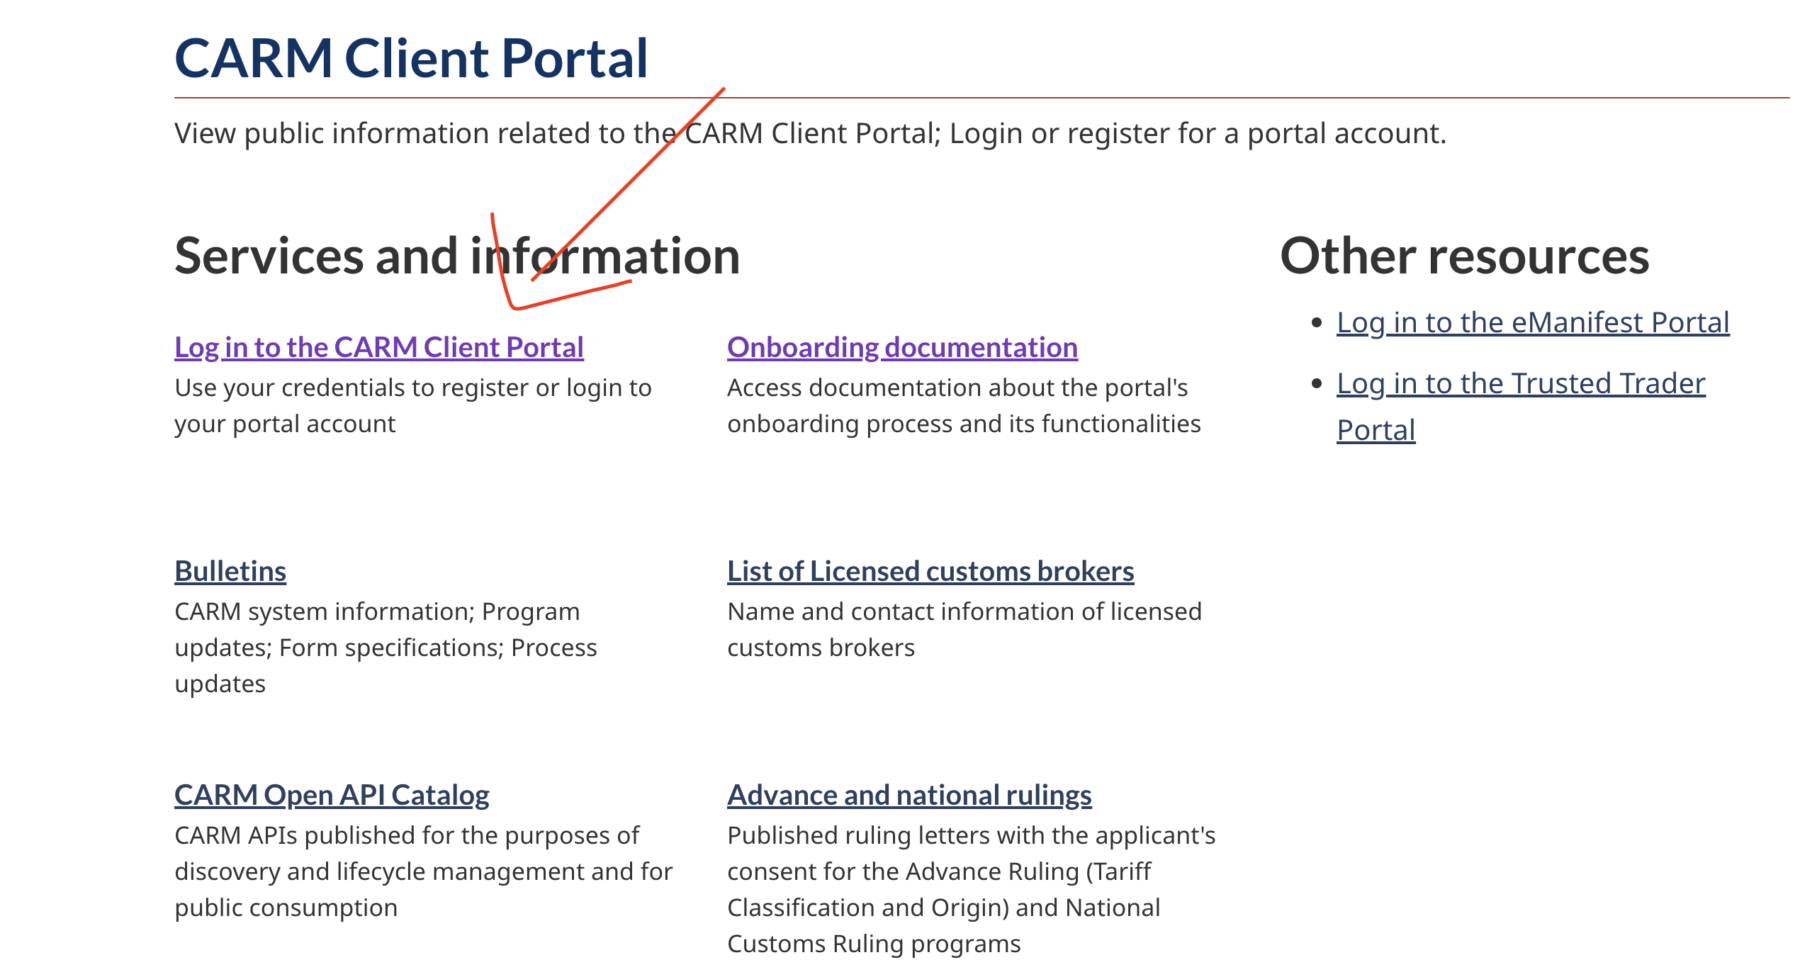
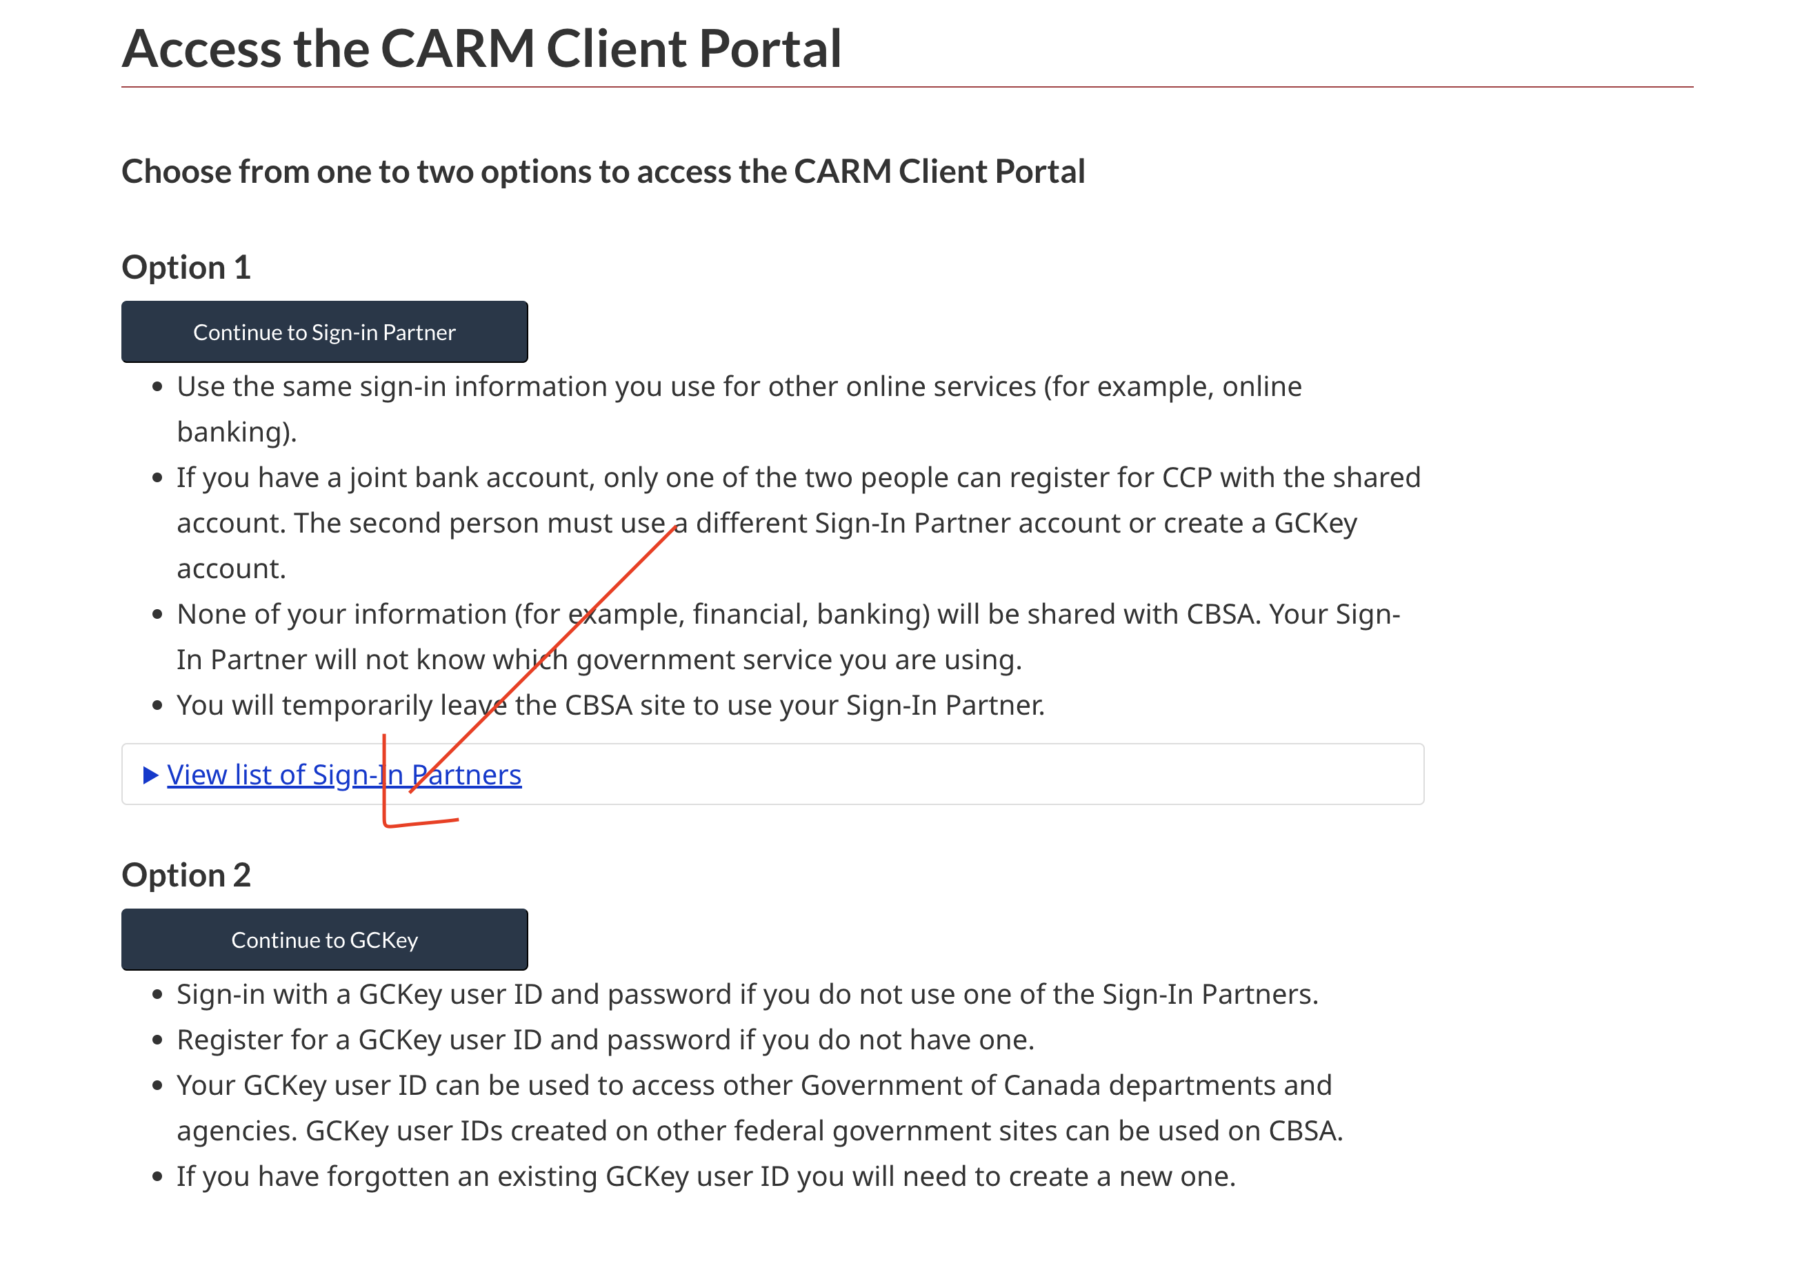
2. Click ‘Option 2: Continue to GCKey’
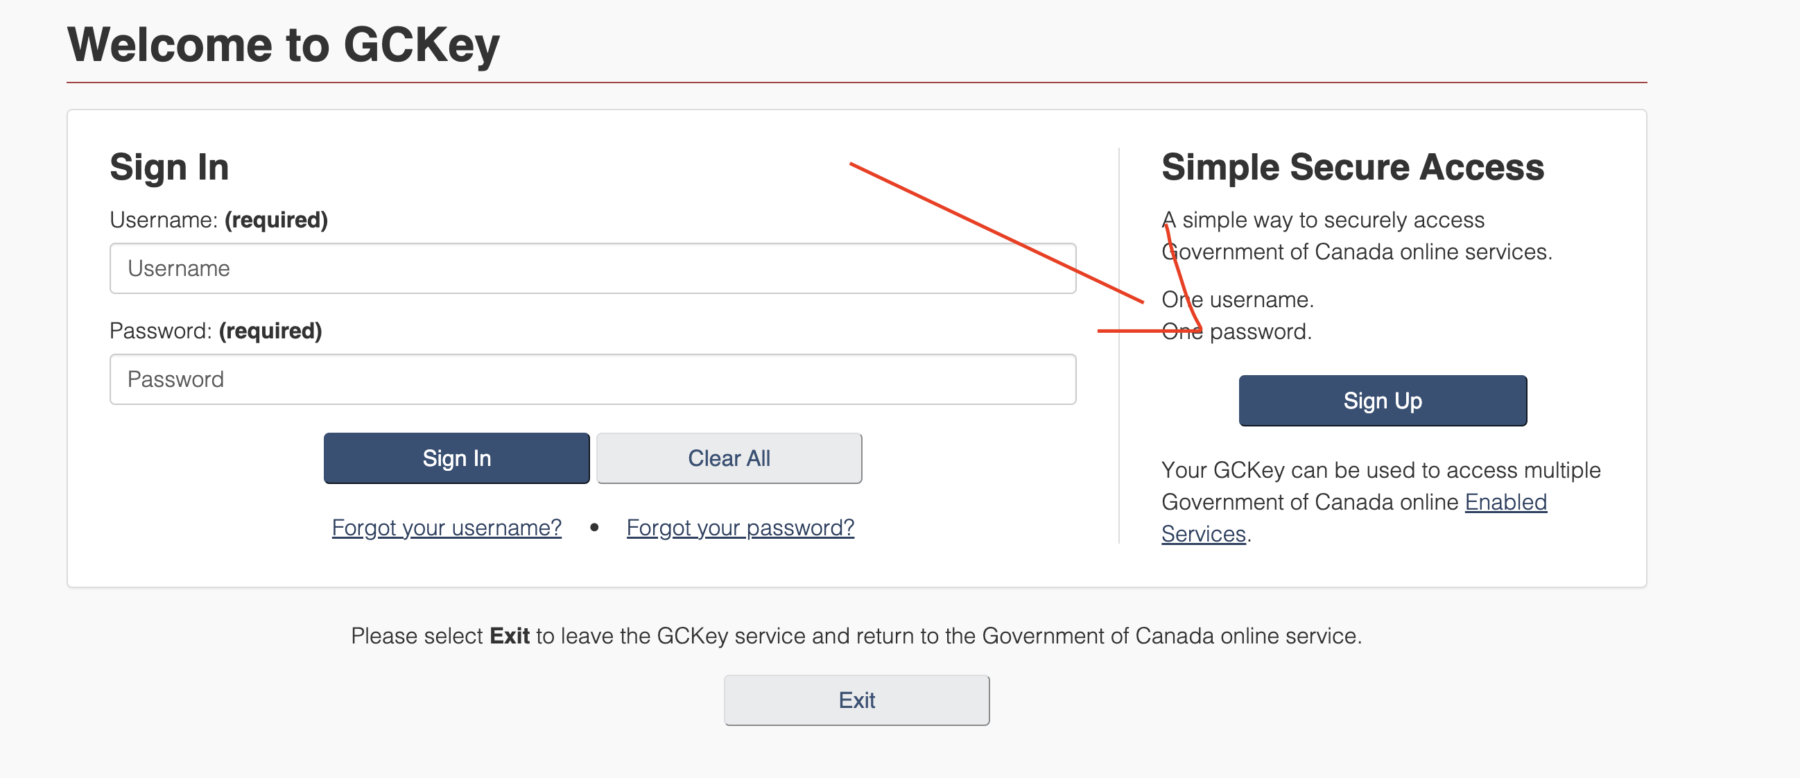
3. Click ‘Sign Up’
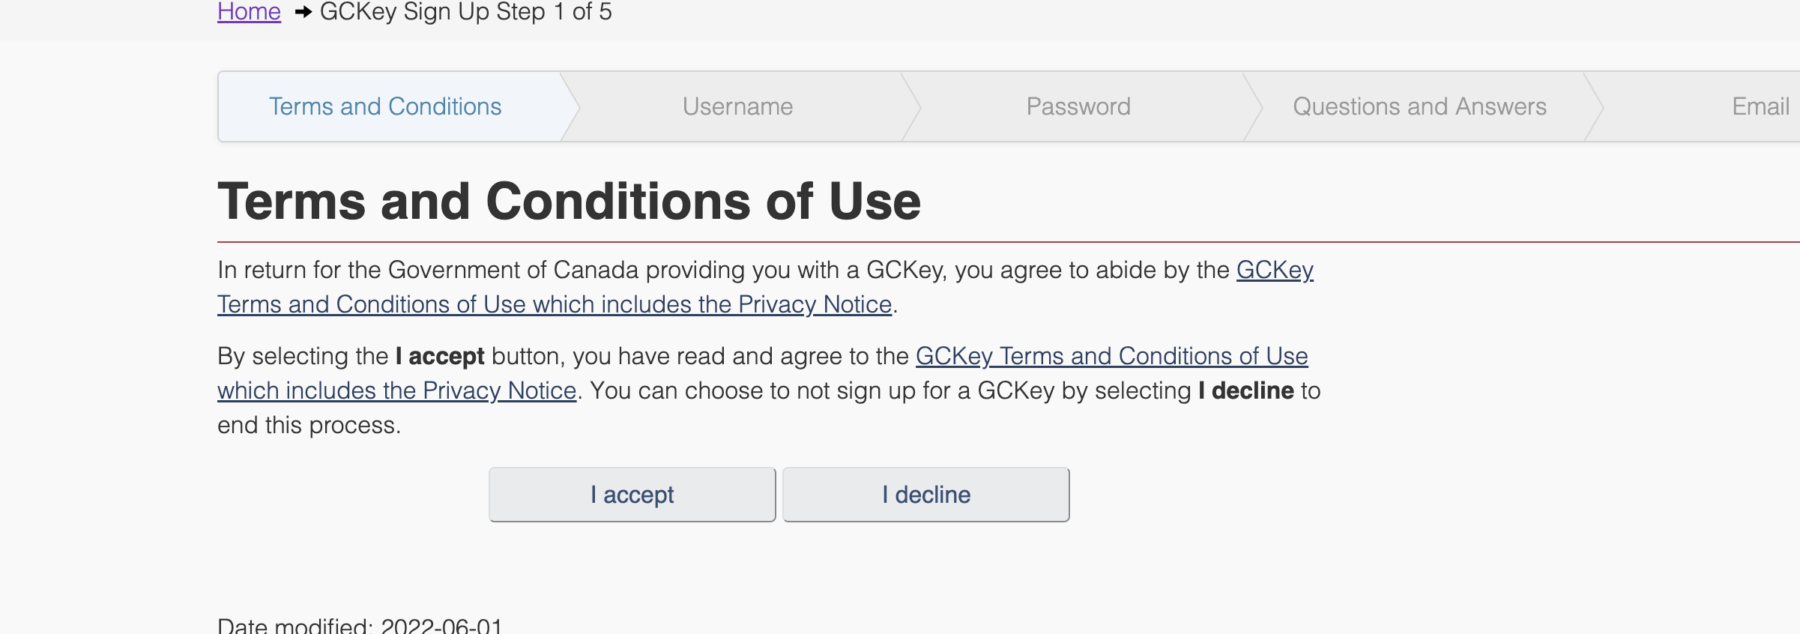
4. Follow the steps to create a user account
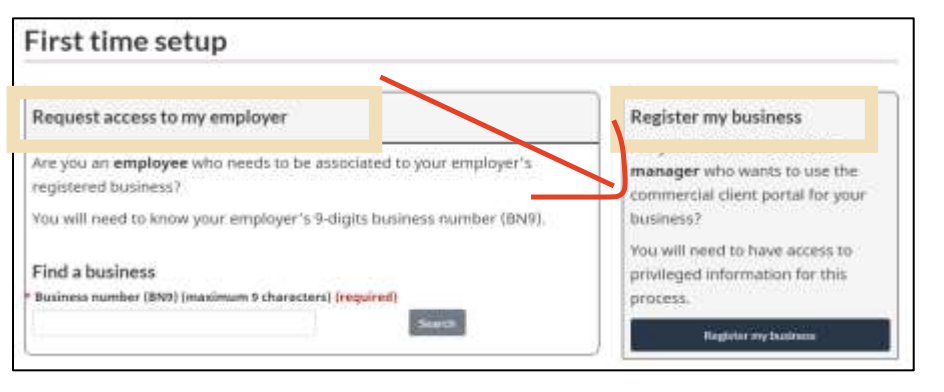
5. Once your individual profile is created, you will be prompted with the ‘First time Setup’ page, from which two options will be available: Request access to my employer, or Register my business. Click ‘Register My Business‘.*
*It is possible one of your colleagues has already created an account for your business. You will be alerted during registration if this is the case (See step 6).
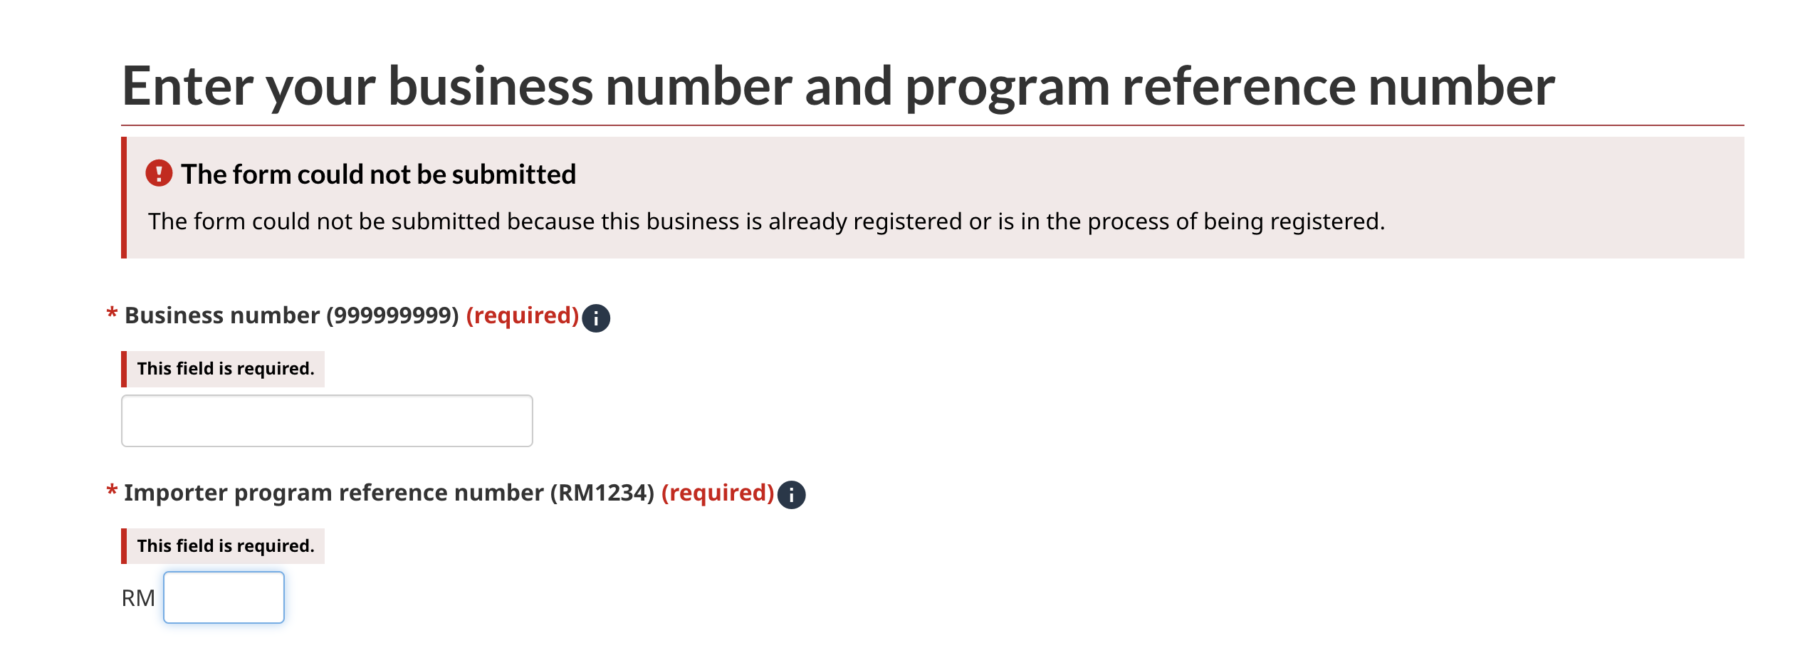
6. During step 5, you may see an error message stating that someone has already activated your business, if that is the case, please follow this guide instead.
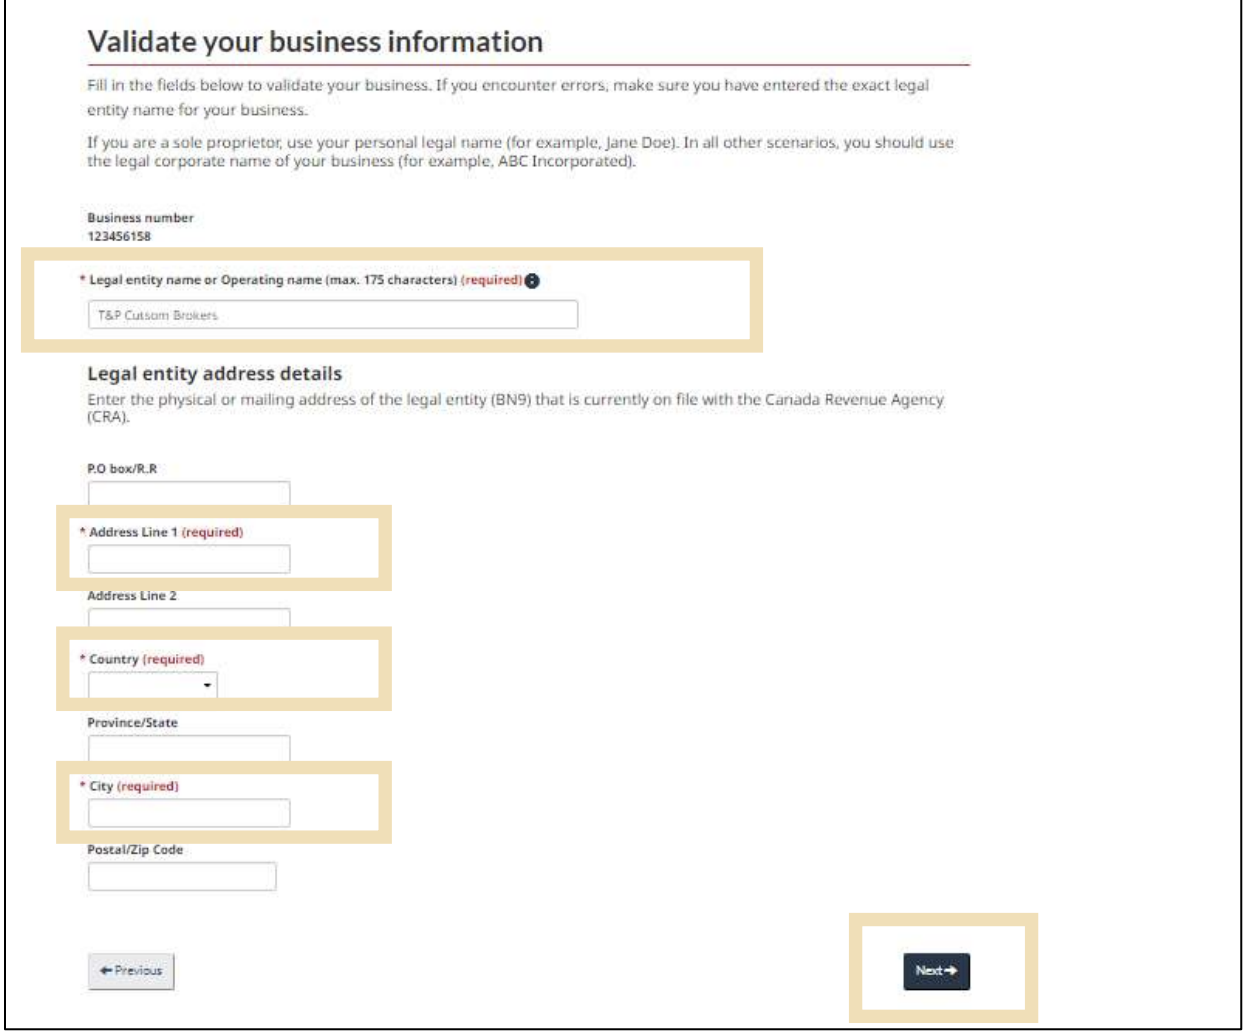
7. Enter the business’ legal name and address. Note that the legal name and address must be exact. This will match what the CRA has on file for your business.*
*If you have issues with this section, we recommend you call the CRA for the fastest resolution. Many businesses have old addresses on file with the CRA.
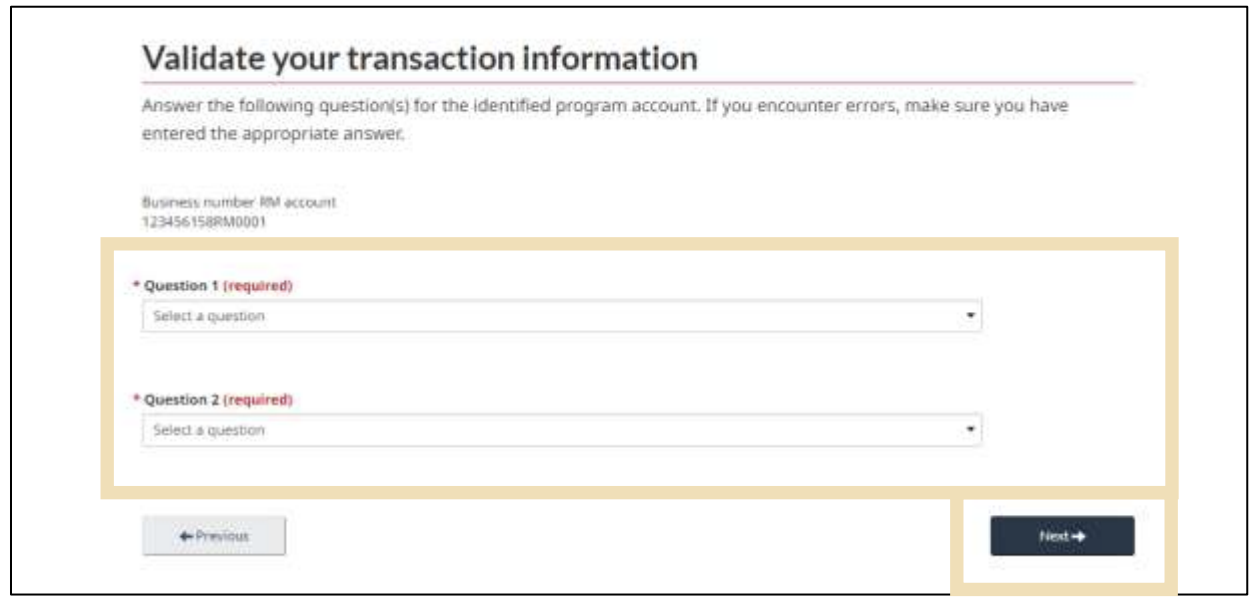
8. Select your preferred security questions. We recommend the following two:
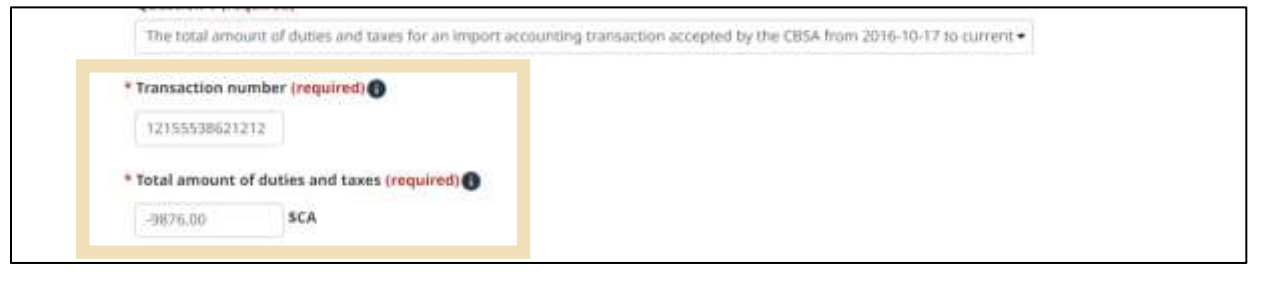
9. For the transaction number question, find a recent invoice from Carson and its associated B3.
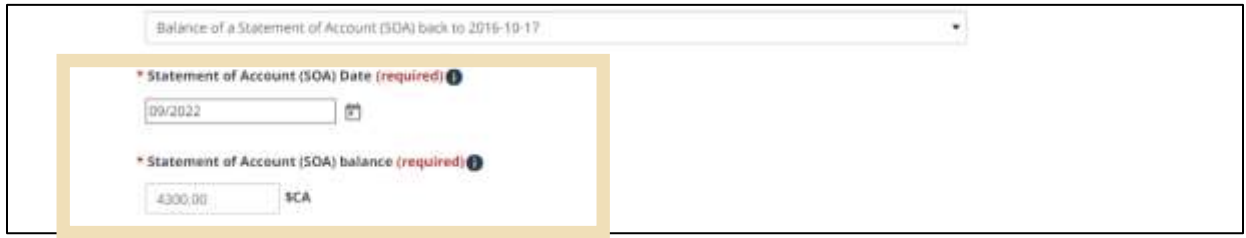
10. For the SOA question, you may require our assistance as not all importers receive a copy of this statement. You may contact our office if you are uncertain.*
*If you cannot reach us, you can also contact the CARM support desk.
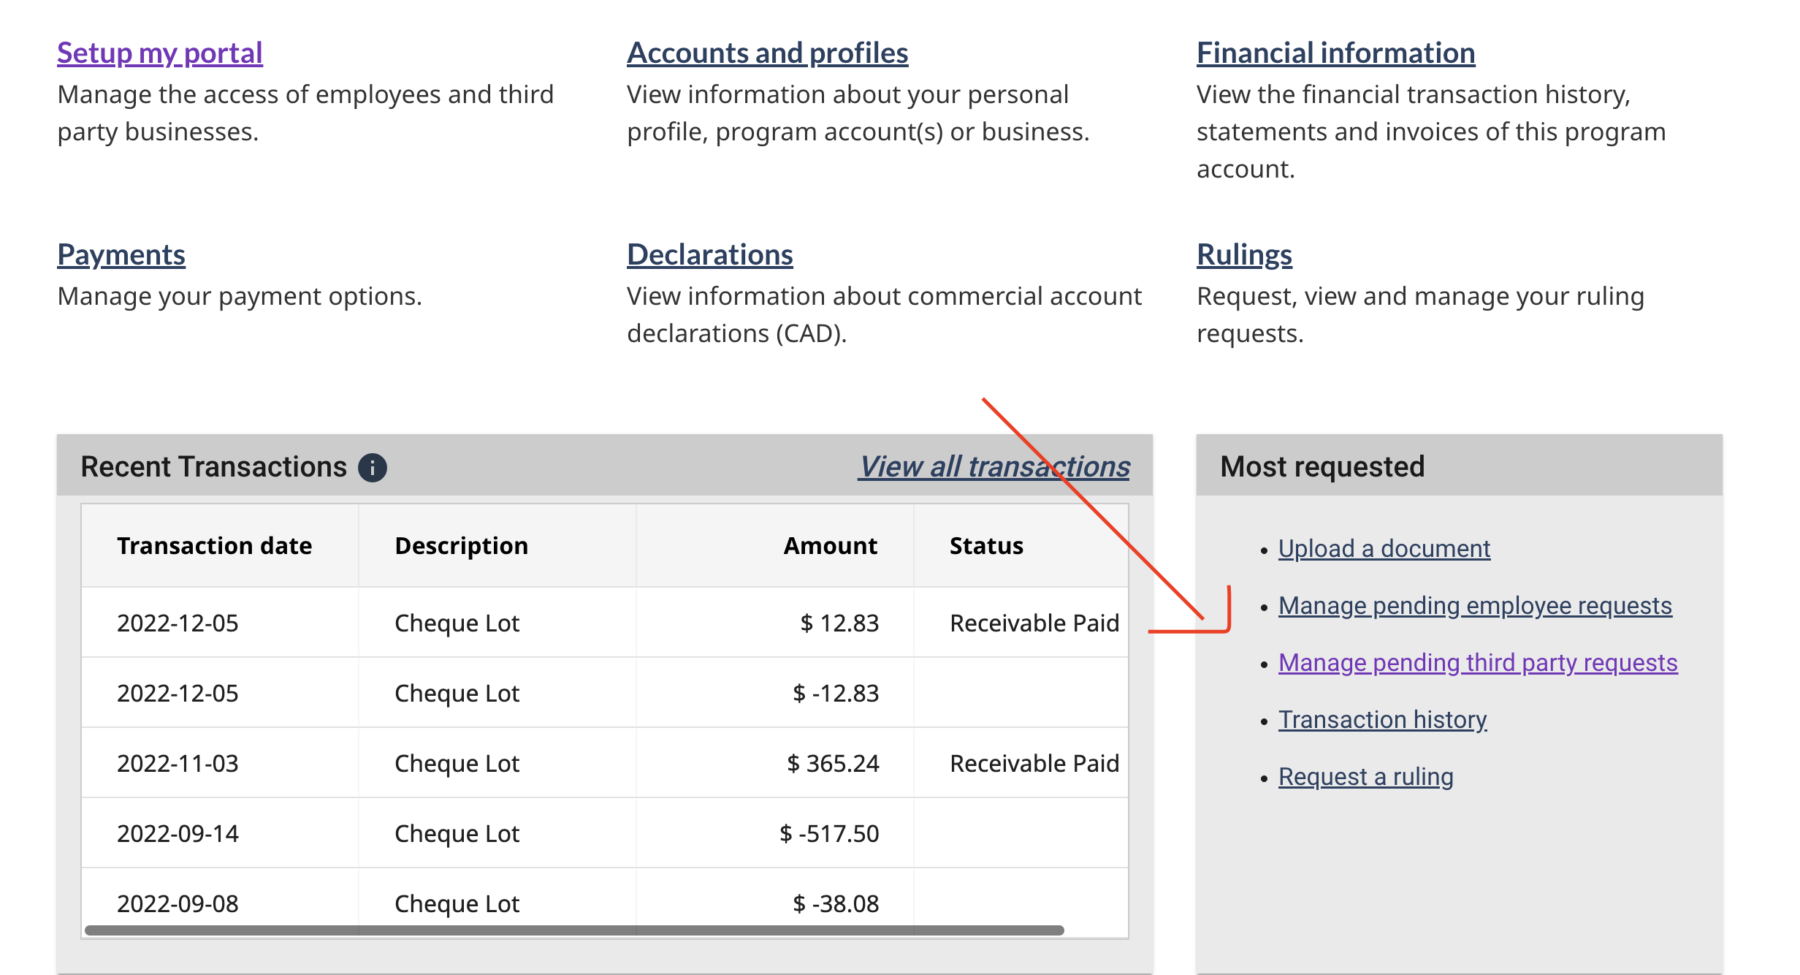
11. Once you have access to the portal, be sure to provide Carson with access so we can continue to serve your account. This can be done by clicking on the ‘Manage pending third party requests’ link.
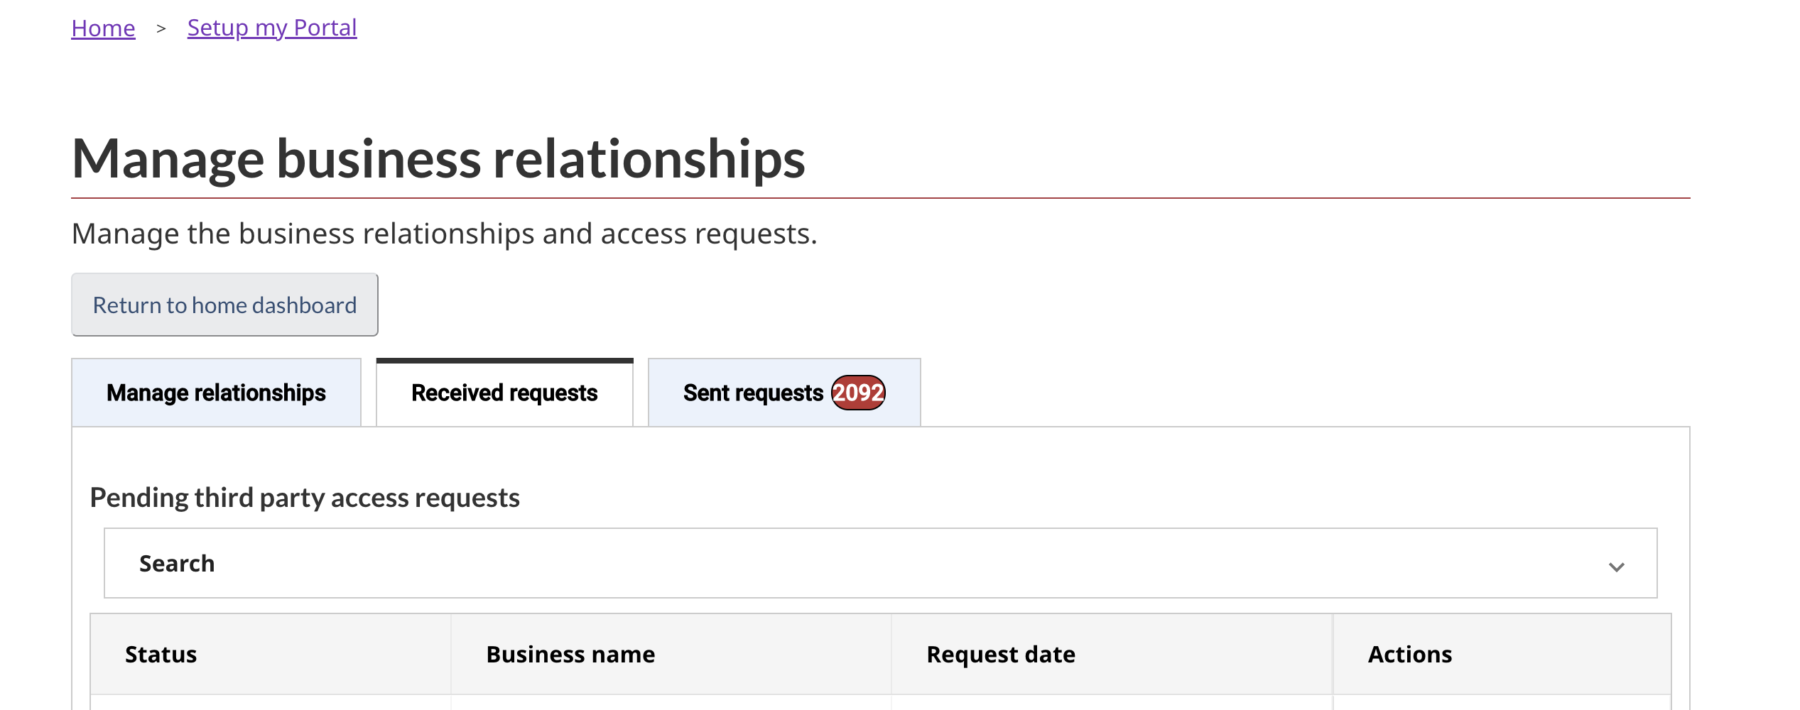
12. In the ‘Received requests’ tab, you should see a request from Carson.
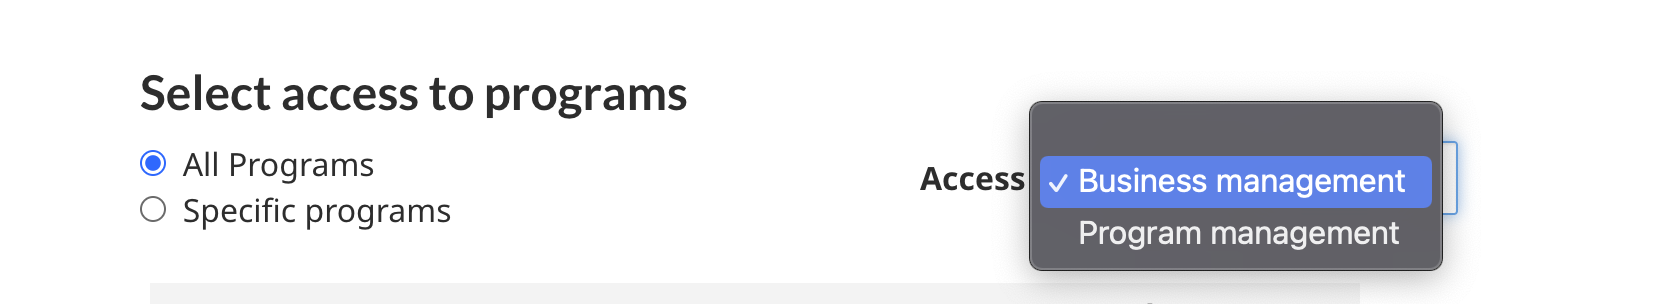
13. Select ‘All Programs’, and ‘Business Management’ as the access type
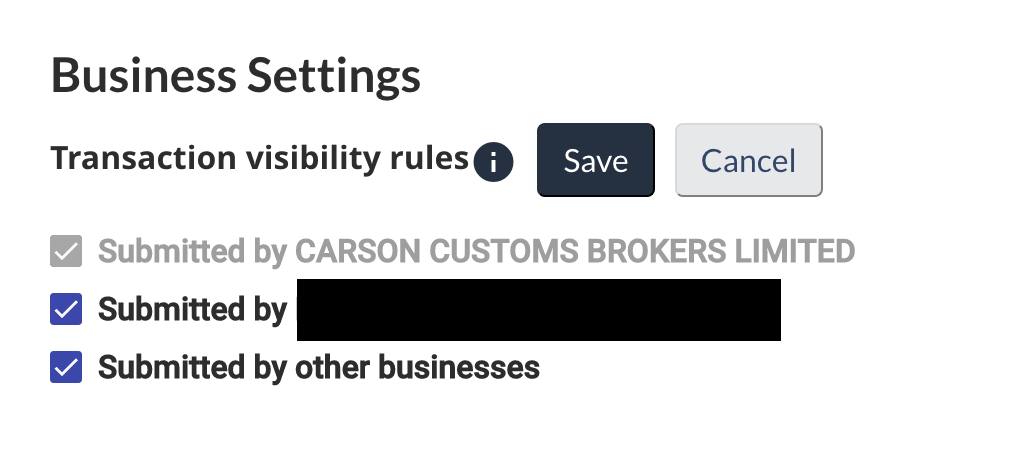
14. For transaction visibility, please check all boxes and click the ‘approve’ button.
*if you are uncertain what visibility or access to grant other providers, please contact us! We can explain exactly what these rules mean.
15. You’re done!
For any additional questions, please call 888-422-7766
On January 5, 2027, new U.S. Customs and Border Protection (CBP) rules take effect impacting importers of record, how they are classified and reported to CBP.
Bond requirements so far remain unchanged, and informal entry remains open to foreign IORs that meet the CTPAT conditions. The executive order calls for higher minimum bonds, limits on continuous bonds for foreign IORs and an informal-entry ban, but CBP has not set a date for these.
CBP released a figure sharing that over a billion dollars in duties is owed from foreign IORs.
For more detail, please review the interim final rule here
Carson encourages clients to review the U.S. IOR criteria now and gather supporting documents, such as proof of ownership and corporate records, as brokers must verify this status before each entry from January 5, 2027.
On October 23, the U.S. President signed a new proclamation that changes which Canadian products are subject to the 50% Section 338 tariffs. The changes apply to goods entered, or withdrawn from warehouse for consumption, on or after 12:01 a.m. ET on October 30, 2026.
What’s new
What stays the same
Please find more details in CBP’s guidance
The list of HS codes modified is here
CBP Form 5106 Importer Account Verification
Since the June 3, 2026 Strengthening Customs Enforcement Executive Order, U.S. Customs and Border Protection (CBP) has increased its checks on importers of record and, since September 18, 2026, has been voiding importer numbers when the information on file is inaccurate or incomplete.
To ensure your account complies with CBP’s increased verification requirements, Carson encourages you to review your importer account details and update your records. A member of the Carson team may contact you to so please have the below ready.
We encourage you to reach out to us proactively if you have not checked your importer information recently to avoid shipment delays and IOR voiding. A new form 5106 will be required in the case of any changes. Please contact acehelp@carson.ca for assistance
On October 23, the U.S. President signed a new proclamation that changes which Canadian products are subject to the 50% Section 338 tariffs. The changes apply to goods entered, or withdrawn from warehouse for consumption, on or after 12:01 a.m. ET on October 30, 2026.
What’s new
What stays the same
Please find more details in the official proclamation. HS lists can be found in Annex I and II.
Questions about how these changes affect your shipments? Contact us at consulting@carson.ca.
U.S. Bars Certain Canadian Alcohol, Dairy and Vehicle Products Starting September 29
As of September 29, 2026 at 12:01 a.m. ET, the U.S. will no longer allow certain Canadian products into the country. Only tariff lines listed in the annexes are covered: Alcohol Annex (Proclamation 11061), Dairy Annex (Proclamation 11062) and Motor Vehicle Annex (Proclamation 11063). The list of barred products includes alcohol, whey, molasses and large motorcycles.
Please check your HS codes against the annexes before September 29 and plan for shipments in transit. Please reach out to Carson with questions about specific products or shipments.
CITT Rescinds Anti-Dumping and Countervailing Duty Order on Chinese Solar Modules
On September 17, 2026, the CITT rescinded its order on photovoltaic modules and laminates from China. Anti-dumping and countervailing duties no longer apply to new imports of these products.
The CBSA will automatically refund these duties paid on eligible goods released on or after March 25, 2026.. For goods released on or after March 25, 2026, any outstanding re-determination process will be terminated and automatic refunds will be applied to those goods.
Goods released before March 25, 2026 are not eligible for a refund due to rescinding of the order. Assessments and reassessments relating to those earlier releases will continue.
Please read the notice for more information, or contact Carson for assistance.
IEEPA tariff refunds – Phase 3 launches October 6 For Early Plaintiffs
CBP has confirmed it will deploy Phase 3 of its CAPE refund program in ACE on Tuesday, October 6. This phase covers the older, finally liquidated entries that the Court of International Trade has ordered CBP to reliquidate, so it applies to importers who filed at the CIT. For importers who filed suit by July 30, you’ll be able to file Phase 3 declarations starting October 6. If your suit began after July 30, CBP says separate instructions are coming
If you didn’t file at the CIT, nothing changes for you here; Phases 1 and 2 remain the route for eligible entries.
CBP is currently sitting on more than 20,000 approved refunds, worth roughly $1.3 billion, that can’t be paid out because the importer never added banking (ACH) details in ACE. If you’re expecting a refund under any phase and haven’t set that up, please reach out to Carson for assistance.
CBP starts voiding importer of record (IOR) numbers this Friday, September 18
Beginning Friday, CBP will void importer numbers where the information on file (CBP Form 5106) is inaccurate or incomplete. A voided number can’t be used to make entry, meaning your shipment stops at the border with no advance warning.
The three things CBP is focused on: your physical business address (not a broker, forwarder, P.O. box or registered agent), an email address that belongs to your company (not a service provider), and a working phone number tied to your business. Non-resident importers and anyone who set up their IOR through a third party are the most likely to have incorrect details on file.
A voided IOR number could take more than 5 business days for the CBP to reinstate, so if you haven’t confirmed your 5106 details recently, please check in the ACE portal or contact us.
Canada’s Counter Tariffs on U.S. Goods Now in Effect
Canada’s counter tariffs on U.S. origin goods are now in effect. Surtaxes of 15%, 25% or 50% apply as of September 8th, and the steel and aluminum surtax increases to 50% for certain goods. The official Customs Notices were published on Sept. 7th and are available below:
Customs Notice 26-23 (United States Surtax Order 2026): https://www.cbsa-asfc.gc.ca/publications/cn-ad/cn26-23-eng.html
Customs Notice 25-11 (steel and aluminum, updated): https://www.cbsa-asfc.gc.ca/publications/cn-ad/cn25-11-eng.html
The official list of HS codes can be found here:
Remission Relief Information for U.S. Counter Tariffs
We are encouraging clients to review the remission options available to them, including applying for an importer-specific remission where impacted goods cannot be sourced elsewhere.
Pending approval of the Governor in Council, it is the government’s intention for the new counter tariffs to benefit from remission in line with existing relief.
For goods not already eligible for remission, the Department is continuing to accept and assess requests for remission under the U.S. Remission Framework, which provides for remission in certain circumstances, e.g., where goods used as inputs cannot be sourced domestically.
Please see below for more information:
Process for requesting remission of tariffs that apply on certain goods from the U.S. – Canada.ca.
Duty Drawback
Duty drawback also remains an option for clients who will be exporting impacted products within four years of import. Please reach out to our drawbacks team at drawbacks@carson.ca to see if your exports are eligible.
Carson is reminding clients to prepare ahead of Canada’s counter tariffs, which are set to take effect following the long weekend, on September 8th. The CBSA has yet to issue an official Customs Notice for the counter tariffs.
The official list of HS codes can be found here:
If you are unsure if these tariffs will affect you, please request an impact report from us (consulting@carson.ca)
Please also review the below information on how to obtain a remission, or claim tariffs through a drawback if surtaxable goods are later exported.
Remission Relief Information for New U.S. Counter Tariffs
In advance of Canada’s upcoming retaliatory tariffs, we are encouraging clients to review the remission options available to them, including applying for an importer-specific remission where impacted goods cannot be sourced elsewhere.
Pending approval of the Governor in Council, it is the government’s intention for the new counter tariffs to benefit from remission in line with existing relief.
For goods not already eligible for remission, the Department is continuing to accept and assess requests for remission under the U.S. Remission Framework, which provides for remission in certain circumstances, e.g., where goods used as inputs cannot be sourced domestically.
Please see below for more information:
Process for requesting remission of tariffs that apply on certain goods from the U.S. – Canada.ca.
Duty drawback also remains an option for clients who will be exporting impacted products within four years of import. Please reach out to our drawbacks team at drawbacks@carson.ca to see if your exports are eligible.
Remission Relief Information for New U.S. Counter Tariffs
In advance of Canada’s upcoming retaliatory tariffs, we are encouraging clients to review the remission options available to them, including applying for an importer-specific remission where impacted goods cannot be sourced elsewhere.
Pending approval of the Governor in Council, it is the government’s intention for the new counter tariffs to benefit from remission in line with existing relief.
For goods not already eligible for remission, the Department is continuing to accept and assess requests for remission under the U.S. Remission Framework, which provides for remission in certain circumstances, e.g., where goods used as inputs cannot be sourced domestically.
Please see below for more information:
Process for requesting remission of tariffs that apply on certain goods from the U.S. – Canada.ca.
Duty Drawback
Duty drawback also remains an option for clients who will be exporting impacted goods from Canada within four years of import. Please reach out to our drawbacks team at drawbacks@carson.ca to see if your exports are eligible.
Impact Reports Now Available For Retaliatory Tariffs
Please reach out to our consulting inbox (consulting@carson.ca) for an impact report to see how Canada’s upcoming Sept. 8th retaliatory tariffs could impact your business (based on prior activity).
The Government of Canada has announced its response to the U.S. Section 338 tariffs and released information on both the proposed counter-tariff measures and support programs for Canadian workers and businesses affected by the tariffs.
The list of products is available below and is set to take effect on September 8, 2026
MPF Increase Effective October 1, 2026
CBP has published its annual inflation adjustment to customs user fees for fiscal year 2027. Effective October 1, 2026, the Merchandise Processing Fee (MPF) will increase as follows:
Other user fees are also adjusting, including the dutiable mail fee ($7.61), express consignment carrier fee ($1.38 per bill), commercial truck arrival fee ($7.60), and permit fee ($190.88)
See here for more details: https://www.federalregister.gov/documents/2026/07/31/2026-15530/customs-user-fees-to-be-adjusted-for-inflation-in-fiscal-year-2027
Following the enactment of section 338 tariffs on Canadian origin goods, PM Mark Carney of Canada provided an update and announced that retaliatory tariffs on U.S. origin goods will arrive in September.
No official details of the tariffs have been released, but according to PM Carney’s announcement sectors such as U.S. steel, dairy, appliances, agricultural equipment, pulp and paper, electronics will be targeted with “dollar for dollar” tariffs
Please read here for more details:
CBP Guidance Issued for Section 338 Tariffs on Canadian Origin Good
U.S. Customs has issued their formal guidance on how the new section 338 tariffs apply on Canadian goods. You can find the full details, including impacted HS codes and chapter 99 details, here.
What Section 338 means for your shipments to the USA: